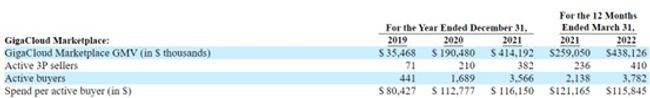
WIKA Books Sales of Rp21.48 Trillion, 20.6% Growth YoY

JAKARTA, Mar 27, 2023 – (ACN Newswire) – PT WIJAYA KARYA (Persero) Tbk. [IDX: WIKA] booked sales of Rp21.48 trillion in 2022, a 20.6% growth year-on-year (YoY) compared with Rp17.81 trillion booked in 2021.

WIKA's President Director, Agung Budi Waskito (Agung BW), said that the largest contributors to WIKA's sales performance were the infrastructure and building segment, followed by the industry segment, energy and industrial plant segment, and finally realty and property segment.

"This achievement shows that WIKA's operations has become more sustained and more efficient. This can be seen from WIKA's project burn rate of 39% in 2022, an improvement from 30.2% in 2021. The Company also recorded a higher gross profit margin of 10.3% in 2022, higher than 9.5% in 2021," said Agung BW.

The good operating performance was a result of WIKA's success in completing domestic projects in 2022, such as the Sukamahi Dam in West Java. WIKA has also completed supporting projects for the G20 Summit, such as revitalisation of VVIP terminals at I Gusti Ngurah Rai International Airport in Bali and Halim Perdana Kusuma International Airport in Jakarta. WIKA has also completed installation of the 50,000 DWT single point mooring in Pengapon, Central Java to improve national energy resilience.

WIKA Sets Transformation Strategy

Following the achievements in 2022, WIKA has set transformation steps to ensure more prudent project selection, adopting lean construction, stronger digitalisation through closer integration of WIKA's BIM capabilities and ERP systems, and strengthening the Company's financial position.

"Through its transformation strategy, WIKA will have a more effective business process to achieve better results for both project owners and the Company," said Agung BW.

PT WIJAYA KARYA (Persero) Tbk. [IDX: WIKA]

Contact Person:
Mahendra Vijaya
Sekretaris Perusahaan
Email: mahendra.v@wikamail.id

Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com

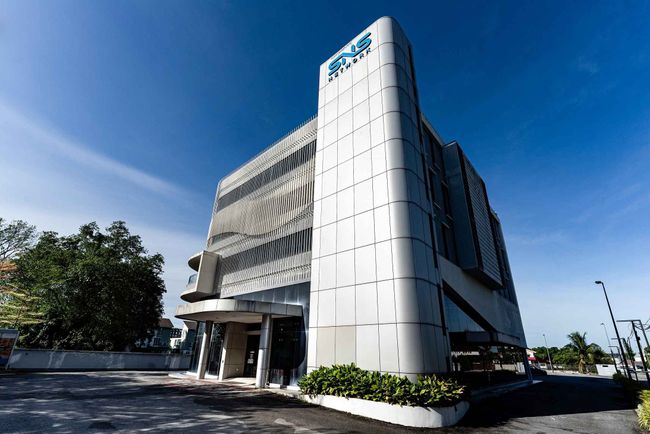
SNS Network Technology Posts 4Q Net Profit Jump of 40.5%

IPOH, Malaysia, Mar 27, 2023 – (ACN Newswire) – SNS Network Technology Berhad, an ICT products, services and solutions provider, today announced that the Group's profit after tax (PAT) for the fourth quarter ended 31 January 2023 (4Q FY2023) increased by 40.5% to RM16.77 million compared with RM11.94 million in the immediate preceding quarter (3Q FY2023).


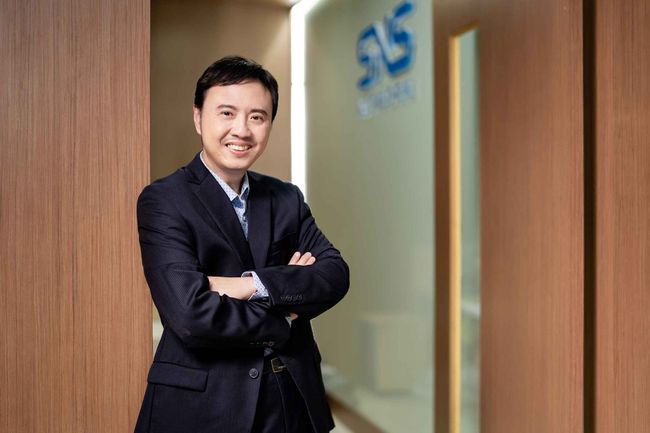
Managing Director of SNS, Ko Yun Hung


SNS recorded revenue that gained 46.2% to RM509.86 million in 4Q FY2023 compared with RM348.84 million in 3Q FY2023. For the quarter under review, there was a 44.6% rise in profit before tax (PBT) to RM22.09 million compared with RM15.28 million in 3Q FY2023.

For FY2023, the Group registered RM43.72 million in PAT as well as PBT of RM57.36 million on RM1.40 billion in revenue. There are no comparative figures on a year-over-year basis as SNS was listed on the ACE Market of Bursa Malaysia on 2 September 2022.

Managing Director of SNS, Ko Yun Hung, said, "The commercial channel of our business remains the mainstay as the Group continued to see commendable growth in revenue and profitability. The demand cuts across industries and is from both the government and private sectors. Just recently we won a tender from the Ministry of Education valued at RM41.33 million through our Device-as-a-Service (DaaS) offering that addresses the gap for learning through the upgrade of devices and technology for students and teachers. Our DaaS offering provides convenience for businesses and organizations, enabling us to support our customers in their digital transformation journey. Additionally, the DaaS business model allows us to retain our customers with a higher likelihood of service renewal and generate recurring revenue for up to five years."

"As we look ahead to the market in the technology industry, we anticipate a growing demand for digital transformation projects. With our expertise in this area and a proven track record of successful implementations, we are well-positioned to secure more projects in the coming months. As businesses and organisations continue to embrace digitalisation, we remain committed to delivering innovative solutions that meet their evolving needs and help them stay ahead of the curve in an increasingly competitive landscape."

The Group has also announced a second interim single-tier dividend of 0.25 sen per share with an ex-date of 10th of May in respect of FY2023 to be paid on 26th of May 2023.

SNS Network Technology: 0259 [BURSA: SNS], https://www.sns.com.my/

Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com

Nissin Foods Announces 2022 Annual Results, Adheres to Premiumisation Strategy to Drive Business Growth

HONG KONG, Mar 27, 2023 – (ACN Newswire) – Nissin Foods Company Limited ("Nissin Foods" or the "Company", together with its subsidiaries, the "Group"; Stock code: 1475) has announced its annual results today for the year ended 31 December 2022.

Results Highlights
— Revenue increased primarily attributable to the organic growth in sales volume of the Group's premium instant noodles throughout the year.
— Maintained a healthy financial position and recommended to declare a final dividend of HK15.16 cents per share.
— The acquisition of remaining 29.55% equity interests in Zhuhai Golden Coast Winner Food Products ("Zhuhai Winner") has given the Group more flexibility to deploy production capabilities in the Mainland China for responding to market demand and the changing business environment, and will in turn increase the overall income and profitability of the Group.

Revenue of the Group increased by 4.1% year-on-year ("YoY") to HK$4,025.0 million (2021: HK$3,866.3 million). Profit attributable to owners of the Group increased by 4.2% YoY to HK$316.5 million (2021: HK$303.8 million), representing a net profit margin of 7.9% (2021: 7.9%). The Group's basic earnings per share increased by 5.5% to 30.32 HK cents for 2022 (2021: 28.74 HK cents).

The Board recommends the payment of a final dividend of 15.16 HK cents per share (2021: 14.56 HK cents), representing a dividend payout ratio of 50.0% (2021: 50.7%) for the year.

Hong Kong Operations
Revenue from the Hong Kong operations increased by 7.4% YoY to HK$1,575.2 million (2021: HK$1,466.2 million), mainly attributable to the implementation of price adjustments and increase in sales volume of premium bag-type instant noodles but was partially offset by the decline in distribution business. Segment results amounted to HK$120.0 million (2021: HK$123.5 million). The decrease was mainly attributable to the continuous increase in logistics and storage costs throughout the year. Revenue from the Hong Kong operations accounted for 39.1% (2021: 37.9%) of the Group's revenue.

As the raw material prices soared during the first half year, the Group adjusted ex-factory product prices in two phases, which helped ease the rising pressures from climbing production costs and raw materials costs. Regarding the performance of instant noodles business, signature brands "Cup Noodles" and "Demae Iccho" attracted positive response from consumers after quality upgrade and sales volume of such products climbed. To further enrich its instant noodles portfolio, the Group launched different new flavours under the "Raoh", Nissin "U.F.O.", "Fuku" and "DOLL" brands. Along with tenets of innovation and creativity, a new W-tab design for regular type of "Cup Noodles" was launched, allowing better cup lid connection with container and greater eating convenience to consumers. Furthermore, a new membership programme "Nissin Foodium" was launched in Wechat Mini Program in Hong Kong in July 2022, aiming to retain existing consumers, boost product sales and allow the Group to better understand consumers' preferences.

On the non-noodle category, the Group's frozen foods business has achieved a decent growth notwithstanding the fierce competition. "KAGOME" business and granola has received remarkable response from new markets in Southeast Asia, especially granola, which has seen sales volume growing considerably in Taiwan and Singapore during the year. Moreover, fresh-cut vegetable business has shown a substantial rise in demand in 2022.

Mainland China Operations
Revenue from the Mainland China operations increased by 2.1% YoY (in local currency: 6.2%), rising from HK$2,400.2 million in 2021 to HK$2,499.8 million in 2022, due to geographical expansion and growth in sales volume of cup-type instant noodles, but is partially offset by a decline in distribution business. Segment results edged up by 4.8% YoY to HK$313.5 million (2021: HK$299.1 million), mainly attributable to the solid performance of instant noodles business, partly offset by the negative impact of the foreign exchange rate of Renminbi. Revenue from the Mainland China operations accounted for 60.9% (2021: 62.1%) of the Group's revenue.

During the year, the Group continued its geographical business expansion strategy in Mainland China and explored certain new markets in the Western and Northern regions of the country. The instant noodles business maintained a sales volume growth amid complicated business environment. The Group once again collaborated with a Japanese anime to launch limited-edition crossover packaging for "Cup Noodles". New SKUs from made-in-Hong Kong "Demae Iccho" brand have been made available in the Mainland China, offering consumers more premium choices. Moreover, new W-tab design for "Cup Noodles" and "Nissin Foodium" Wechat Mini Programme were introduced to consumers. In Mainland China, "Nissin Foodium" is also an e-commerce platform.

In November 2022, the Group acquired the remaining 29.55% equity interest in Zhuhai Winner, allowing it to consolidate control over Zhuhai Winner. The acquisition of remaining 29.55% equity interests in Zhuhai Winner has given the Group more flexibility to deploy production capabilities in the Mainland China for responding to market demand and the changing business environment, and will in turn increase the overall income and profitability of the Group.

Although the performance of joint venture distribution business in Shanghai has been inevitably affected during the year by lockdowns, the Group seized the opportunity from pandemic rampant to expand product categories, covering frozen and chilled food such as frozen pasta and ramen, resulting in a considerable growth in the sales volume of frozen foods. Furthermore, benefiting from consumers' rising awareness of health consciousness, the sales of "KAGOME" vegetable and fruit juice and granola products gathered stronger growth momentum.

Prospects
The Group is cautiously optimistic about the long-term business development in the regions and continues to look into ways to alleviate the cost pressure under this competitive landscape. Consumer consumption in the Mainland China continues to improve as per capita spending rises and the per capita income gap between urban and rural residents is narrowed. The Group plans to enlarge the connection with consumers at the locations with heavy flow of people such as retail outlets and transportation hubs, after the recovery of consumers' mobility from pandemic. Moreover, the Group continues to expand its business territory and penetrate into other areas alongside the development of additional sales channels. In Hong Kong, Nissin Foods expects tourism rebound following the border reopening of Mainland China will further revive the local economy, helping invigorate higher purchasing power and consumption sentiment.

To further consolidate overall competitiveness, the Group has been actively implementing automated, robotic and smart technology at its production plants to realise digitalisation for the purpose of improving operational efficiency, productivity, product quality and customer experience.

Mr Kiyotaka ANDO, Executive Director, Chairman and Chief Executive Officer of Nissin Foods, said, "We've gained valuable experience in adapting to challenging circumstances swiftly from the pandemic in the past three years. The pandemic has put our businesses through rigorous tests which in turn proves the resilience of our strategic direction towards flexible operational and management practices.

"Stepping into 2023, as anti-pandemic restrictions are lifted, the economy is expected to stage a visible rebound. In leveraging our solid foundation and footholds in Hong Kong and Mainland China, as well as the rich and diversified product portfolio that we have developed over time, Nissin Foods will adhere to its premiumisation strategy and provide good-quality food that delivers contentment and enjoyment to its valuable customers, while realising continuous and long-term growth."

About Nissin Foods Company Limited
Nissin Foods Company Limited (the "Group"; Stock code: 1475) is a renowned food company in Hong Kong and Mainland China with a diversified portfolio of well-known and highly popular brands and the largest instant noodle company in Hong Kong. The Group officially established its presence in Hong Kong in 1984. The Group primarily manufactures and sells instant noodles, frozen foods and other food products under its two core corporate brands, namely "NISSIN" and "DOLL" together with a diversified portfolio of iconic household premium food brands. The Group's five flagship product brands, namely "Cup Noodles", "Demae Iccho", "Doll Instant Noodle", "Doll Dim Sum" and "Fuku" are also among the most popular choices in their respective food product categories in Hong Kong. In the Mainland China market, the Group has introduced technology innovation through the "ECO Cup" concept and primarily focuses its sales efforts in first-and second-tier cities.

Nissin Foods is a constituent of eight Hang Seng Indexes, namely: Hang Seng Composite Index, Hang Seng Consumer Goods & Services Index, Hang Seng Stock Connect Hong Kong Index, Hang Seng Stock Connect Hong Kong MidCap & SmallCap Index, Hang Seng Stock Connect Hong Kong SmallCap Index, Hang Seng SCHK Mainland China Companies Index, Hang Seng SCHK ex-AH Companies Index, and Hang Seng Small Cap (Investable) Index. Nissin Foods is eligible for trading under Shanghai-Hong Kong and Shenzhen-Hong Kong Stock Connect. For more information, please visit www.nissingroup.com.hk.


Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com

Chu Kong Shipping Announces 2022 Annual Results

HONG KONG, Mar 27, 2023 – (ACN Newswire) – Chu Kong Shipping Enterprises (Group) Company Limited ("Chu Kong Shipping", or the "Company", together with its subsidiaries, the "Group"; Stock Code: 560.HK) is pleased to announce its annual results for the year ended 31 December 2022 (the "Year").

During the Year, benefited from the improved profitability of its terminal logistics business, including a significant increase of warehouse storage business and value-added services, the Group achieved a substantial increase in annual profit and remarkable results of business expansion. The Group's consolidated turnover increased by 27.8% year-on-year to HK$2,899.5 million (2021: HK$2,268.4 million). In line with the growth in consolidated turnover, profit for the Year increased remarkably by 63.0% year-on-year to HK$108.0 million (2021: HK$66.3 million) and the profit attributable to equity holders of the Company was HK$93.5 million (2021: HK$44.1 million), representing a significant increase of 112.1% as compared to the same period last year.

The board of directors of the Company resolve to propose a final dividend of HK4 cents per ordinary share. In commemoration of the Company's 25th listing anniversary and appreciation for the shareholders' undivided support, a special dividend of HK2 cents per ordinary share was proposed.

Business Review
In 2022, the rebound of the COVID-19 epidemic ("epidemic") situation remained continuous, resulting in greater downward pressure on the global economy. Yet, benefited from the effective implementation of the new development concept of "Domestic-international Dual Circulation" in the People's Republic of China ("PRC"), the PRC's logistics industry has recovered at a relatively fast pace and the market scale has also steadily expanded which strongly supported the smooth and orderly operation of various areas of the industrial chain and livelihood consumption businesses. Meanwhile, the cross-border passenger business has recovered steadily with the gradual relaxation of the anti-epidemic policy. Compared with the same period last year, the Group's terminal logistics business progressed well, with both increases in the break bulk cargoes transportation volume and handling volume. The waterway passenger transportation business has been transformed actively in facing difficulties by developing new routes and exploring new business opportunities.

Focusing on Upgrades of Logistics Strategy and Actively Supporting Hong Kong to Fight against the Epidemic

The Group continued to leverage on advantages of the terminals' network within the Guangdong-Hong Kong-Macao Greater Bay Area and adhered to synergistic development on both domestic and foreign trade businesses. The profitability of the terminal logistics business has continually enhanced, and the scale of integrated logistics, cross-border e-commerce, and air freight logistics businesses has continually expanded.

During the Year, regarding the cargoes transportation business, the break bulk cargoes transportation volume reached 678,000 tons, representing a year-on-year increase of 3.5%. The container transportation volume for the Year reached 1,285,000 TEU, while the volume of container hauling and trucking on land for the Year recorded 200,000 TEU. For the cargo handling and storage business, the volume of container transportation was 1,131,000 TEU, while the volume of break bulk cargoes handling volume during the year was 10,209,000 tons, representing a year-on-year increase of 30.0%.

Besides, the Group fully implemented its strategic plans, continued to optimise its business models. There was a steady improvement in operating efficiency of Zhaoqing, Foshan, Qingyuan, Zhuhai, Zhongshan and Hong Kong regions. Driven by strong growth in break bulk cargoes, Foshan and Zhongshan regions recorded explosive growth of 403.0% and 239.6% respectively. In Zhaoqing region, Zhaoqing New Port Production and Operation Centre were officially launched and Gaoyao Port actively developed new sources of goods such as precision machinery and furniture products. Foshan region Gaoming Port opened a new mode of "trans-customs" transportation business between Gaoming Port and Guangzhou Baiyun International Airport, and successfully launched the cross-border e-commerce direct purchase and export business. In Zhuhai region, the official launch of the "Doumen-Shekou" combined port project enabled Doumen Port to fully utilise its resources to attract foreign trade enterprises in the region, while the acceptance process of the imported fruits at the designated fruit supervision sites was completed. Civet Port developed the sand and gravel handling business continuously and pioneered shipping e-commerce.

Taking the new warehouse as an important strategic pivot, Chu Kong Transhipment & Logistics Co., Ltd. ("CKTL"), has leveraged its strength in resources to develop emerging businesses, deepen the cooperation between cargo terminals and navigation, and promote the transformation and upgrade. The new warehouse in Tuen Mun commenced operation smoothly, in turn, continued boosting the growth of the warehouse storage business of CKTL. CKTL successfully undertook the integrated logistics business for clients such as Sinopharm Holdings Guangzhou Co., and also completed the renovation and upgrade of the supervisory warehouse of Cathay Pacific America Line. The Group has successfully put its Yau Ma Tei construction logistics loading, unloading and distribution base in operation, and rapidly developed the local construction logistics business in Hong Kong. CKTL has successfully implemented multiple large-scale construction logistic projects, and has taken advantage of the opportunity to upgrade the "Huangpu-Hong Kong" building materials logistics line. While the regular line for the waterway e-commerce logistics between Shenzhen and Hong Kong was successfully launched, CKTL also completed the construction of the integrated operation platform for ports and barges with the Zhaoqing region.

During the Year, the Group has fully leveraged its business advantage as a combination of "transit + port" in the Guangdong-Hong Kong-Macao Greater Bay Area, and successfully opened up "Green Passages" and "Synergised Passages" for waterway transportation to secure a full logistics chain, which in turn efficiently supplied anti-epidemic medical materials, anti-epidemic quarantine facilities, as well as the daily necessities such as fresh food and grocery items. During the Year, a total of 20 Guangdong-Hong Kong transportation routes were opened-up by the Group to support Hong Kong in the fight against the epidemic, the total accumulated capacity of 68 barges and 168,000 container cargoes is recorded, with a cumulative volume of 650,000 tons of livelihood and anti-epidemic materials were supplied to Hong Kong.

Enabling Upgrading of Airport Strategy while Passenger Transportation Business Gradually Recovered

Despite the impact of the epidemic, Chu Kong Passenger Transport Company Limited ("CKPT") still recorded an increase in business compared with last year, the local ferry business recorded a total number of passengers of 11,339,000.

The Group concentrated its superior resources and actively participated in the bidding for new projects of the Hong Kong International Airport. The Group made every effort to prepare the launching of the new routes between the Shenzhen Airport and the Hong Kong International Airport, further capturing the opportunities in the cross-border passenger transportation market in the Guangdong-Hong Kong-Macao Greater Bay Area. During the Year, the Group actively promoted the upgrading of airport strategy and achieved breakthroughs in the airport business. Hong Kong International Airport terminal services Limited, a subsidiary of the Group, won the bid for the project of passenger and baggage services in the transit terminal of the Hong Kong International Airport, thereby the Group's cross-border airport passenger service will be expanded from the original "sea-air intermodal" to "sea-land-air intermodal". Hong Kong International Airport related service businesses, which were developed previously by CKPT, have maintained normal operations under the impact of the epidemic, among which, the car-sharing business on the apron of the Hong Kong International Airport has maintained a steady growth. CKPT officially signed the code-sharing development and coordination agreement with Hong Kong Express, and completed the launching of the product as well. The Group achieved the completion of code-sharing cooperation with the three major base airlines, Cathay Pacific, Hong Kong Airlines and Hong Kong Express.

Promoting the Upgrading of Hong Kong Strategy and Achieving Remarkable Results in Business Expansion

Regarding water cultural tourism business, Orient Pearl Cruise Company Limited ( "Orient Pearl" ) successfully obtained the Hong Kong Travel Agency License, and its sightseeing cruise "Orient Pearl" has obtained the qualification for berthing in Central Pier No.8 in Hong Kong. Moreover, "Orient Pearl" continued to carry out the trial berthing training at Central Pier, and has now obtained the qualification for berthing at Central Pier No. 8. At the same time, the Group completed the construction of box offices in the core areas of Hong Kong and obtained the Hong Kong Travel Agency License, which creates favourable condition for the Group to accelerate the innovation and upgrade of water-based tourism projects.

As to the fuel supply business, Sun Kong Petroleum Company Limited ("Sun Kong Petroleum") actively developed its business in the unfavourable environment of the epidemic. In addition to successfully developing the business in the storage and operation of Castrol's lubricant, Sun Kong Petroleum achieved growth in sales volume of both diesel and engine oil during the year, turning a loss into a profit against the odds, thus laying a solid foundation for the Group to continue to deepen its strategy in Hong Kong.

Prospects
In early 2023, Hong Kong, Macao, and Mainland China officially resumed normal traveller clearance, and multiple cross-border waterway passenger routes operated by the Group across Guangdong-Hong Kong, as well as across Hong Kong-Macao, have resumed operation. As the movement of cross-border personnel and material flow has gradually resumed normal, the market environment will be further improved, so a new wave of business growth is expected for the Group's business.

Focused on the objective of becoming a first-class waterway public transportation service provider and a first-class full-scope logistics services provider in the Guangdong-Hong Kong-Macao Greater Bay Area, the Group will continue to take advantage of its strength in resource integration, promote innovation and development in terminal logistics, optimise the strategic layout of passenger transportation segment, and develop new routes under new quality agency service. Moreover, the Group will actively carry out material acquisition projects with an aim to improve the overall profitability of the Group. Firmly grasping the strategic opportunities brought by the national "14th Five-Year Plan", the Guangdong-Hong Kong-Macao Greater Bay Area development, as well as the "Belt and Road" initiative, the Group will accelerate the strategic transformation of the enterprise in the following areas:

Firstly, the Group will promote the transformation of its business operation model for better structure and greater synergy. The Group will fully leverage the integrated role of CKTL as a transhipment hub, optimise the business layout, integrate inner port resources, consolidate development synergy, and continue to enhance the overall competitiveness of its terminals. The Group will also accelerate the implementation of integrated management for its cross-border waterway passenger transportation business and continue to optimise cross-border passenger transportation routes.

Secondly, the Group will promote the transformation of its warehousing and storage services business to a larger scale and higher efficiency. The Group will further build a professional platform for the construction logistics centre, expand the construction logistics services business related to the construction projects in Hong Kong, and simultaneously develop the building materials supply business. Besides, the Group will vigorously develop its modern logistics businesses, including air freight logistics, supply chain logistics, cold chain logistics, duty-free product storage, etc., to promote the development of its logistics business to be an extension of the modern industrial chain by forming a comprehensive supply chain logistics network. Moreover, the Group will accelerate the establishment of logistics business outlets in the ASEAN region, acquisition of investment projects of synergistic value, as well as establishment of overseas bases, and will actively explore the markets along the "Belt and Road".

Thirdly, the Group will promote the transformation of its Hong Kong local businesses for service enhancement and better branding. The Group will deeply integrate into the Hong Kong airport business circle, actively participate in the bidding for the strategic quality projects related to the Hong Kong International Airport, and strive to become a comprehensive service provider for the Hong Kong International Airport. The Group will also delve into the exploration of the market potential of its local public transportation business in Hong Kong and continue to expand the new local ferry services. In addition, the Group will persistently build up the brand of "Oriental Pearl" by carrying out advertising and sponsoring campaigns on vessels, increasing advertising and marketing efforts, and continuing to expand the cultural tourism market.

Fourthly, the Group will promote the transformation of its waterway passenger transportation and other auxiliary businesses for better business models and greater resilience. The Group will firmly grasp the new development opportunities in the resumption of cross-border waterway passenger transportation, and endeavour to carry out the operation resumption of important cross-border routes such as routes between Guangzhou Pazhou to Hong Kong, and Shenzhen Airport to Hong Kong. The Group will also actively participate in the bidding for the oil supply in the sea project of the Hong Kong Government, strive for new agency business in lubricant storage, and expand the fleet for lubricant shipping.

About Chu Kong Shipping Enterprises (Group) Company Limited
Chu Kong Shipping is a listed company incorporated in Hong Kong held by Chu Kong Shipping Enterprises (Holdings) Company Limited and subject to Guangdong Provincial Port & Shipping Group Company Limited. Chu Kong Shipping operates and manages the largest high-speed passenger fleet and network of waterway passenger transport in Guangdong, Hong Kong Macau which is based in Hong Kong and covered cities in the Guangdong-Hong Kong-Macao Greater Bay Area namely Guangzhou, Shenzhen, Shunde, Zhongshan, Dongguan, Macau and so on. Since the acquisition of Sun Ferry Services Company Limited in May 2020, CKSG has entered the local ferry market in Hong Kong, providing services on five main inner harbour and outlying island ferry routes, and developing the Victoria Harbour water cultural tourism projects simultaneously. Chu Kong Shipping is also one of the largest operators of inland terminal and logistics service in the PRD. Based in Hong Kong, Chu Kong Shipping builds up a network covering multiple cities in the PRD, including Zhaoqing, Qingyuan, Foshan, Guangzhou and Jiangmen etc., providing the operation of inland cargo terminals, integrated logistics, international forwarding and solutions to logistic supply chain and so on.

For more information, please visit: https://www.cksd.com/


Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com
Krypto Miners Club Releases Revolutionary NFT Collection Backed by BTC Mining on Polygon Blockchain

DUBAI, Mar 26, 2023 – (ACN Newswire) – Krypto Miners Club (KMC), a leading blockchain-based company, has released phase one of their highly anticipated NFT collection on the Polygon Blockchain. The four-phased project includes 8,888 NFTs, each with unique attributes and features. KMC aims to provide a decentralised platform for crypto mining, enabling users to earn rewards while contributing to the security and stability of the blockchain network.


The first phase consisted of 2,222 NFTs out of which almost 70 percent of the NFT's were sold during the whitelist mint. The remaining 688 NFTs are now available for public minting.

KMC is on a mission to build true passive income with reliable , sustainable and constant cash flow.The Krypto Miners recognise the importance of reducing the carbon footprint and have implemented eco friendly practices to achieve this goal. With 8,888 NFTs generating sustainable & multiple streams of income, the NFTs will be an inheritance to pass on to the next generation.

Krypto Miners will release the next 2,222 NFTs from phase two on the Polygon Blockchain as soon as phase one is sold out. With the overwhelming response from investors, phase 2 is expected to be as popular as the first phase, if not more.

The Krypto Miners Club is focusing on creating long-term passive income for their NFT Holders which is backed by BTC mining. "We are thrilled to see such an overwhelming response to our KMC NFTs," said Yashodan Patil, CEO of Krypto Miners Club. "Our community is at the forefront of the cryptocurrency mining industry , and were excited to offer a new and innovative way for individuals to participate in this rapidly evolving space.This is a great accomplishment for the team who have invested a significant amount of time and resources in developing a project that meets the needs and preferences of its target audience."

The Krypto Miners are committed to sustainability and efficient mining practices which has resulted in increased profitability for their NFT owners, and are excited to share their success with the world. With years of experience and expertise they have established themselves as a trusted and reliable provider of mining services.

The team will focus on creating a long term sustainable system for their holders regardless of the fluctuations of the market. The company's commitment to excellence, combined with the innovative use of blockchain technology, has already made the NFT collection a hit among investors and collectors alike.

Mint your NFT's: www.kryptominers.club/mint

About The Krypto Miners

A community driven NFT collection project backed by BTC mining. The Krypto Miners Club, a project focused on creating long-term passive income for our NFT Holders. With 8888 NFTs generating sustainable & multiple streams of income for years, the NFTs will be an inheritance to pass on to the next generation. NFT holders will be rewarded in BTC from revenue generated by BTC mining farm.

For more information contact:
Info@kryptominers.club

Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com
Prime Miami Bayfront Site Announced by Urban Core

MIAMI, FL, Mar 26, 2023 – (ACN Newswire) – The Urban Core Division, led by Mika Mattingly and Cecilia Estevez, proudly announces the availability of a prime Miami bayfront development site. Located at 400 Biscayne Blvd., in the heart of Downtown Miami, the site currently holds an 11,600 sq. ft. state-of-the-art sales center sitting on an 18,062 sq. ft. lot that claims over 157 ft. of frontage with unimpeded views of Biscayne Bay.


400 Biscayne Blvd Location
– bayfront view development site located at 400 Biscayne Blvd, in the heart of Downtown Miami.


Mika Mattingly, Executive Vice President, states, "This is a rare opportunity to acquire a prime bayfront development site in the heart of Downtown Miami. The site is zoned T6-80-O, Miami's most intense zoning code, allowing up to 80 stories and 1,000 units per acre by right, with opportunities to increase both height and density through Miami21 Bonus programs."

The property has proposed plans by architect Sieger Suarez for a 74-story luxury condominium building consisting of 408 units. The site's liberal T6-80- O zoning code allows for 415 units by right and includes an additional 82 units transferred from the adjacent Elser development, bringing the total buildable units to 497.

Downtown Miami is rapidly becoming a global destination, attracting affluent individuals and some of the most prominent financial and tech-based companies in the world. The site is conveniently located near Miami's most prominent attractions and developments, including Miami Worldcenter and The Waldorf Astoria Residences.

The location is a tourist hotspot, attracting over 4 million tourists annually within a 1/2 mile radius. 400 Biscayne is strategically situated near the largest cruise port in the US and Miami's Brightline train station – a high-speed rail station that connects to Aventura, Boca, Fort Lauderdale, West Palm Beach, and Orlando.

This prime development site offers a unique opportunity for investors and developers to capitalize on the continued growth of Downtown Miami. Its close proximity to major attractions, transportation hubs, and a burgeoning financial and tech scene make it an attractive prospect for luxury residential development.

With its unparalleled location and zoning potential, the 400 Biscayne site is poised to become an iconic addition to the Miami skyline, further solidifying Downtown Miami's status as a global destination for affluent residents and tourists alike.

For more information about this rare development opportunity, visit 400biscayne-blvd.com or contact Mika Mattingly and Cecilia Estevez at the Urban Core Division.

About The Urban Core Division

With a distinct focus on South Florida's dense urban markets, the Urban Core Division is a full-service commercial real estate brokerage providing sales and advisory services to owners, investors, and developers. Driven by powerful local neighborhood data and unrivaled industry connections, the team leverages its far-reaching network of professionals to position commercial properties for maximum market exposure. For additional information, visit 400biscayne-blvd.com.

Contact Information
Mika Mattingly
Commercial Real Estate Broker
mika@urbancoredivision.com
(786) 486-4391

SOURCE: Urban Core

Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com
Tianyun International Announced 2022 Annual Results

HONG KONG, Mar 24, 2023 – (ACN Newswire) – Tianyun International Holdings Limited ("Tianyun International", together with its subsidiaries, the "Group") (Stock code: 6836.HK) a leading seller and manufacturer of processed fruits products in China, is pleased to announce its audited annual results for the year ended 31 December 2022 ("Year Under Review"). Being a consumer goods company, the annual results of the Group demonstrate stable revenue and profit, and showcase successful achievements in R&D and innovation, introduction of new product categories, enhancement of brand reputation, expansion of production capacity planning, sales network, and development strategies for the future. The Group recorded a revenue of approximately RMB680.7 million, a gross profit of approximately RMB189.8 million and a net profit of approximately RMB96.6million, with gross profit margin improved to 27.9%. In view of the Group's strong overall financial position and the steady improvement in its core competitiveness of the business, the Board recommends a final dividend of HK$0.05 per share for 2022.

Being a role model for the industry with award-winning quality
Shandong Tiantong Food Co., Ltd. ("Shandong Tiantong Food"), a wholly-owned subsidiary of the Group, was awarded the "Certificate of High-tech Enterprise" by the Shandong Provincial Department of Science and Technology, the Shandong Provincial Department of Finance and the Shandong Provincial Taxation Bureau of the State Administration of Taxation and will continue to enjoy the preferential policies of the State on income tax exemption for high-tech enterprises.

The Group also received the title of "Excellent Quality and Safety Management Enterprise" jointly awarded by Shandong Entry-Exit Inspection and Quarantine Association and other organisations. Meanwhile, Shandong Tiantong Food received the honorary titles of "Social Responsibility Model" and "Advanced Enterprise of Outstanding Contribution" of the canned food industry for the Thirteenth Five-year Plan as well as "Top 10 Enterprises (Export)" in China's canned food industry by the China Canned Food Industry Association ("CCFIA")., in recognition of the Group's outstanding contribution in the three-year special campaign to build a brand in China's canned food industry. Moreover, the Group was once again selected as a 2022 municipal-level "Specialized, Excellent, Featured and Innovative" Enterprise by the Linyi Municipal Bureau of Industry and Information Technology. The above honours represent a tremendous recognition of the Group's comprehensive strength.

Enhanced marketing of own brands with new products widely recognised by the market
The Group has a series of own brands, including "Bingo Times", "fruit zz", "Tiantong Times", "Shiok Party" and "Demon Fruit Season", enabling it to enhance its brand image in an all-round manner. Progress has been made in various aspects such as product diversification, packaging diversification and production de-seasonalisation. Meanwhile, the Group has actively responded to the ever-changing consumer market, continuously improved product quality, upgraded product packaging, and incorporated more fashion and leisure elements. The Group also actively enriched its product series. The Group identified the recent rise in demand for canned yellow peaches in the market and responded by launching new product lines, such as "Chinese trend style" canned peaches, Zodiac-branded canned fruit products, and brown sugar canned pears. In addition, in response to the significant growth of the functional beverage market in recent years and the expansion of consumption scenarios, the Group developed a range of specialty beverages to enhance its competitiveness in this area and optimized its product offerings.

The Group capitalized on an opportunity to significantly refine its marketing strategy and bolstered its engagement with consumers by launching various promotional activities. These efforts have resulted in enhanced brand image and increased sales of its own brand products. Currently, the Group's own brand products are available for sale in 27 provinces, municipalities, and autonomous regions across China, and the Group continues to utilize a "online + offline" sales model. The Group has established a presence on several popular online shopping platforms as its primary sales channels and has also partnered with online live-streaming entertainment platforms during major events like "Double Eleven" and "New Year's Eve" to increase its market visibility, strengthen its brand promotion, and execute wide-reaching marketing campaigns. Looking forward, the Group plans to fully leverage on the advantages of digital technologies to further facilitate online sales of its own brand products.

Focus on OEM and the sales of fresh fruits business development
The Group's OEM business has exhibited steady development. Over the years, the Group has maintained close partnerships with globally renowned food brands and traders. Given the sustained demand for "Made in China" processed fruit products in foreign markets, the Group plans to actively seek out additional high-quality customers in developed countries and regions like Europe, Australia, New Zealand, Japan, the United Kingdom, the United States, and Canada, in order to expand its share in the international market.

The sales of Chinese fresh fruits always have advantages both locally and overseas, and the Group has accumulated many years of experiences in this regard. The Group plans to diversify its fresh fruit product portfolio and expand its sales network to other regions. In addition, the Group's Yunnan production base is situated amidst plenty fruit resources, allowing the Group to source and process a greater variety of exotic fruits and vegetables from tropical regions. This, in turn, will provide consumers with a wider selection of high-quality, diverse fruit and vegetable products.

Actively research and develop new production techniques and construct new workshops and bases to expand production capacity
To enhance its production capacity and achieve sustainable growth, the Group has been actively investing in research and development of new products with independent core technologies, as well as continuously improving its production techniques. As a leading high-tech enterprise in the industry, the Group successfully developed two new specialty beverages during the review period: vitamin sports drinks with fruit pieces and fruit enzyme sports drinks. The vitamin sports drink is a beverage that contains fruit pieces processed from fruits, which can improve energy metabolism and alleviate fatigue. The fruit enzyme sports drink uses peaches, apples, and other raw materials to provide enzymes that meet daily nutritional requirements and is aimed at promoting better health. With the completion of R&D, the Group is entering the preparatory stage of production and sales for these two new products, which will soon be launched in the market, offering consumers more diversified choices.

The Group has been actively expanding its production capacity. The Shandong production base has made continuous improvements in its production facilities, increasing output and enhancing efficiency through automation. The installation of new production workshops No. 5 and No. 6 is nearly completed, which will significantly expand the production capacity of both new and existing processed fruit products. Additionally, the construction of the Yunnan production base began in 2022 and is expected to be partially operationalby the end of 2023. This is a significant step for the Group's development in China's tropical climate region, as it will comprehensively expand the Group's overall production capacity, improve logistics and warehousing, and offer customers a wider variety of processed fruit products and specialty beverages. The Yunnan production base will work in tandem with the Shandong production base to increase the production and sales of tropical, subtropical, and temperate processed fruit products and beverages.

Mr. Yang Ziyuan, Chairman and CEO of the Group said, "In the aftermath of COVID-19, as the world gradually reopens, the Group has focused on creating value, improving risk management, and enhancing operational efficiency. The Group aims to seize the opportunities presented by the restoration of normalcy by investing in R&D, developing new product categories, improving product packaging and design, and expanding its distributor network. These efforts will not only boost the Group's revenue and profitability but also provide customers and consumers with a greater variety of fruit products and specialty beverages. As the Group strengthens its capabilities and expands its investment in sales channels, it will prioritize diversified product categories and a robust brand portfolio as a core business strategy. Additionally, the Group will pursue domestic and international M&A opportunities and strategic partnerships to broaden its sources of revenue, promote a diversified development model, enhance its brand influential power, and reputation globally. By doing so, the Group will achieve sustainable growth and offer consistent and sustainable returns to its shareholders and investors."

About Tianyun International Holding Limited (Stock Code: 6836.HK)
Tianyun International Holdings Limited (the "Company") and its subsidiaries (collectively referred to as the "Group") are principally engaged in (i) the research and development, production and sales of processed fruit packaged in metal containers, plastic cups, glass containers and aluminum foil bags and beverages ii) trading of fresh fruit. Processed fruit products are sold both under its own brands "Bingo Times", "fruit zz" and "Tiantong Times" and on an OEM basis. The beverages are sold under its own brand Shiok Party "Shiok Party" and "Demon Fruit Season".

The Group has been consistently committed to providing its customers with healthy and safe products. As a food enterprise with one of the most complete quality certifications, we rigorously adhere to stringent international production standards and are accredited with BRC (A), IFS Food (High), FDA(FSMA), SC, KOSHER, SMETA and ISO9000, etc. in respect of our production facilities, quality control and management. The Group has also passed the internal food production standards reviews and audits from several UK and US supermarket chains. At the same time, as a Chinese "Equal production line; Equal standard; Equal quality" food production and export enterprise, the Group has been supplying products of consistent quality to domestic and international markets. Since 2016, the Group's own-brand processed fruit products have continued to achieve high market recognition, and have also been awarded the honor and qualification of "China Canned Product Quality Certification Label" by national associations.

The Group was awarded China's Most Promising Listed Companies by internationally-renowned financial magazine Forbes, and the "2017 Linyi Mayor Quality Award" by the PRC government in 2017. The Group's new and proprietary researched, developed and produced pure fruit snack food received a national "Certificate of Invention Patent" in 2018. In 2019 and 2022, the Group was awarded the national Hi-tech Enterprise Certificate consecutively. In 2020, the Group was recognised as one of the Most Valuable Chinese Brands for the fourth consecutive year.

For more information, please visit www.tianyuninternational.com


Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com
Analogue Grows FY2022 Revenue and Contracts Awarded by 21.0% and 41.8% Respectively Defying Challenging Market Conditions

HONG KONG, Mar 24, 2023 – (ACN Newswire) – Analogue Holdings Limited ("Analogue" or the "Company", together with its subsidiaries, collectively the "Group") (stock code: 1977), a leading electrical and mechanical ("E&M") engineering service provider in Hong Kong, today announced its annual results for the year ended 31 December 2022 ("the Year" or "FY2022") with growth in revenue and contract awarded, achieving solid trading performance despite impact from global economic adversity and the lingering pandemic.

Highlights
— Total revenue reached HK$6,474.7 million, an increase of 21% year-on-year
— Contracts awarded during the year grew by 41.8% year-on-year to HK$6,822 million
— Contracts-in-hand rose to a high of HK$11,656 million
— Profit attributable to owners of the Company was HK$114.6 million
— The Board has resolved to pay a special dividend of HK4.5 cents per share as a special celebration of the 45th Anniversary of the Group

During the Year, the Group's total revenue increased by 21.0% year-on-year to HK$6,474.7 million. Gross profit rose by 15.2% to HK$1,011.5 million, with gross profit margin at 15.6%. Profit attributable to owners of the Company for FY2022 was HK$114.6 million. If excluding the provision for litigation liabilities of HK$150 million and the impairment loss on Group's interest in an associate of HK$75.6 million, the FY2022 profit for the year would be HK$340.2 million, representing a year-on-year increase of 8.2%.

The Group's contracts-in-hand increased to approximately HK$11,656.3 million as at 31 December 2022, providing a strong foundation for the core businesses' growth in the immediate term. Tendering activities remained active throughout the Year, with a total of 1,409 tenders or quotations valued at over HK$1 million each.

The Board did not recommend a payment of a second interim dividend for the year ended 31 December 2022. The Board has resolved to pay a special dividend of HK4.5 cents per share for FY2022 as a special celebration of the 45th Anniversary of the Group.

Dr. Otto Poon Lok-to, Chairman of Analogue Holdings Limited, said, "The business environment in 2022 has proved to be even more challenging than in preceding years, with the growing geopolitical tensions, the Russia-Ukraine conflict, rising inflation and interest rates contributing to global supply chain disruptions and material shipment interruptions, coupled with strict pandemic control measures in Hong Kong and Mainland China, resulting in project delays. Even so, the market demand for E&M engineering services remained strong. Backed by our three strategic pillars of 'New Technology', 'New Market', and 'New Business Model', we were able to sustain business growth owing to our industry-leading position, diversified business portfolio, innovative technologies and strong financial position."

Building Services segment's contracts-in-hand increased by 11.1% to HK$5,438 million as of 31 December 2022. The Group's exceptional project execution capability enabled it to deliver on the order book throughout FY2022, boosting the segment revenue by 26.0% to HK$4,257 million. In particular, the recurring revenue stream from infrastructure operation, data centres, and housing programmes was fortified by the HK$415 million of new maintenance contracts secured in FY2022, up by 111.7% year-on-year. While the Group's proprietary ATAL Building Services Prefabrication and Modularisation ("ABSPM") construction technology was successfully completed in a number of contracts during the Year, a number of key projects were secured, including three projects related to the Three Runway System at Hong Kong International Airport with a total value of over HK$800 million. The Group also successfully completed the largest data centre project of its team in a decade, with a value of over HK$1,000 million. Ongoing operation and maintenance ("O&M") contracts for the aforementioned data centre were also secured, worth over HK$70 million. Demand for available space in data centres in Hong Kong is expected to double over the 5 years from 2022. Highlighted by a significant market share and continued recognition from prestigious customers, the Group remains at the forefront in the field of data centres.

Environmental Engineering segment's contracts-in-hand amounted to HK$4,791 million. During the Year, the Group won seven new contracts that underscore its expertise in project management services for quality water, wastewater, and solid waste infrastructure. Priding itself on innovation and technology advancement, the Group advanced its proprietary "Digital Twin technology" for monitoring the influent quality of incoming sewage at a sewage plant in one of its wastewater project sites, enhancing optimisation of its operational efficiency. In addition, two projects in which the Group participated received international awards, namely, O PARK1, the first organic resource recovery centre in Hong Kong, which was awarded the National Overall Winner and FIRE Category Winner in the "Energy Globe Award 2022" for its outstanding performance in adopting innovative design to tackle climate change; and the Yuen Long Effluent Polishing Plant project of the Drainage Services Department, which was awarded the "2022 Edmund Hambly Medal" from the Institution of Civil Engineers, U.K. for its excellence in adopting innovative design to combat climate change. Furthermore, a wastewater treatment plant project in Croatia was secured during the Year, an important step in establishing the Group's expertise in water infrastructure projects overseas. Leveraging its proven technical and project management capabilities, the Group is well-positioned for a major growth opportunity in the years to come.

Information, Communications and Building Technologies ("ICBT") segment's contracts-in-hand increased slightly to HK$888 million during the Year. Revenue increased by 27.6% year-on-year to HK$631 million, thanks to its strong order book. Continuing to support Hong Kong's "Smart City" and "Smart Economy" visions, the Group provides green and intelligent building solutions that integrate a wide range of information and communications technologies with AI-enabled Digital Twin, energy and management technologies, ESG dashboard, Indoor Environment Quality Management, robotic solutions, and Smart Lampposts. The Group has been awarded another contract of the smart lampposts pilot scheme for deploying smart lampposts across Hong Kong, marking a milestone towards the city's visionary goal of smart city development. Recognised as a key player in new technology, the Group's comprehensive AI Energy Management Platform, Internet of Things ("IoT") applications, Video Analytics technology, and "walkable" Photovoltaic ("PV") were adopted in a new world-class smart office and commercial building being constructed in Hong Kong's prestigious Central Business District. The Group's IoT-based smart hostel solutions will also be installed at one of the largest and most prestigious universities in Hong Kong. The Group will continue to invest in digital transformation across smart building technologies and roll out innovations in a timely manner.

Lifts and Escalators segment's contracts-in-hand amounted to HK$540 million. During the Year, Anlev Elevator Group ("Anlev"), the Group's global brand of lifts, escalators, and moving walkways, secured strategic orders ranging from mass transportation in Brazil and hotels in Mexico, prestige government offices in Hong Kong, to orders in Mainland China, the US and other countries in Asia. The Group's wholly owned subsidiary Anlev (UK) Limited has also taken significant steps towards establishing itself in the United Kingdom's high rise lift market by obtaining safe contractor and construction supplier accreditations and finalising the order for the iconic and prestigious residential Victoria Riverside project in Manchester, United Kingdom. The Group will seek new distributors in the United States, Europe, Middle East and Southeast Asia to further its global expansion plan. In parallel, the Group is completing a RMB60 million expansion of its Nanjing factory facilities to increase production capacity for lifts and escalators to meet the anticipated demand and growth of its global business.

"Over the decades, the Group has grown in tandem with Hong Kong, overcoming many challenges and helping make our city a smarter and more sustainable place. To deliver many more years of success, digitalisation and embedding sustainability into every aspect of business is key. With our strong emphasis on innovation, R&D capability and ESG strategies, Analogue is well-positioned to provide solutions to support our clients in achieving their ESG goals, optimising energy consumption and reducing their carbon footprint. To enhance efficiency and prepare for the future, operating units were re-organised and new appointments as well as procedures were established. We are continuing to provide staff training, as well as enhancing staff engagement to directly tackle the industry shortage of labour. We will also make good use of technologies to boost safety, quality and productivity," added Dr Poon.

The Group's strong tender activity in 2022 is evidence of the high market demand and opportunities for growth that will support its further development and expansion in 2023. In the coming years, Hong Kong will continue to develop as a smart and sustainable city. The business opportunities that emerge from this process will allow the Group, supported by its proprietary technologies, to bring benefits to its customers and Hong Kong through its projects, including energy-efficient buildings, digital solutions to improve operational efficiency, and improved healthcare and other service delivery for the betterment of Hong Kong.

Dr Poon concluded, "While we are mindful of the many global and local challenges experienced over the past year, numerous developments such as the reopening of Mainland China's borders and committed public projects spending by the Hong Kong Government present valuable opportunities to the E&M engineering sector. Having already established footholds in the United States and Europe, the latter via the United Kingdom, we will develop organically in the two regions while concurrently looking out for M&A and equity participation opportunities that can promote synergies among our businesses and create healthy income sources."

For more details of the 2022 Annual Results, please refer to the announcement that has been filed with The Stock Exchange of Hong Kong Limited.
https://www1.hkexnews.hk/listedco/listconews/sehk/2023/0324/2023032401303.pdf

About Analogue Holdings Limited
Established in 1977, Analogue Holdings Limited is a leading electrical and mechanical ("E&M") engineering service provider headquartered in Hong Kong, with operations in Macau, Mainland China, the United States and the United Kingdom. Serving a wide spectrum of customers from public and private sectors, the Group provides multi-disciplinary and comprehensive E&M engineering and technology services in four major segments, including Building Services, Environmental Engineering, Information, Communications and Building Technologies ("ICBT") and Lifts & Escalators.

The Group also manufactures and sells Anlev lifts and escalators internationally and has entered into an alliance with Transel Elevator & Electric Inc. ("TEI"), one of the largest independent lifts and escalators companies in New York, the United States. The Group's associate partner, Nanjing Canatal Data Centre Environmental Tech Company Limited (603912.SS), is specialised in manufacturing of precision air conditioners.


Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com
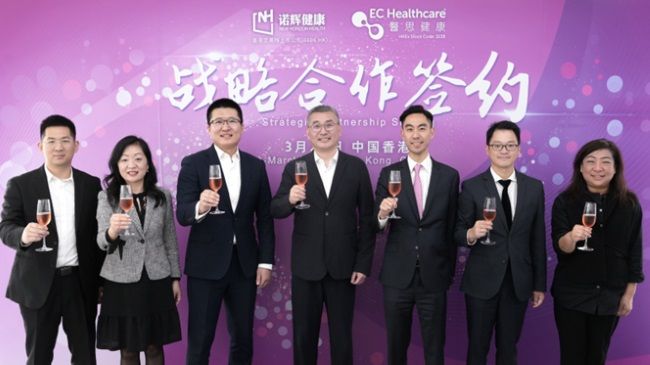
EC Healthcare Collaborates with New Horizon Health to form Strategic Partnership To Jointly Launch CerviClear in Hong Kong

HONG KONG, Mar 24, 2023 – (ACN Newswire) – EC Healthcare (2138.HK) and New Horizon Health (6606.HK) host ceremony today to form an exclusive strategic partnership. Both parties will consolidate the resources to empower the launching, distribution, and promotion of CerviClear in Hong Kong. It is expected this home-use cancer screening product will help to increase the awareness penetration of Cervical cancer prevention, and achieve better prevention efficacy. Under the Partnership, EC Healthcare is the exclusive partner of New Horizon Health.


Left to right: Mr. ZHENG Weixian Senior Director of Operation management, New Horizon Health, Dr. Rita Shih Head of International R&D Center, New Horizon Health, Mr. Li Yan Vice President, New Horizon Health, Mr. Zhu YeQing Chairman and CEO, New Horizon Health, Mr. Leslie LU Executive Director and Co-Chief Executive Officer, EC Healthcare,Dr. Eric CHU Chief Business Officer, EC Healthcare, Dr. Julie CHOW Chief Proposition Officer (Healthcare), EC Healthcare


Cervical cancer is a common malignant tumor for women. The morbidity and mortality have been rising in recent years, with a notable trend of rejuvenation. Cervical cancer is also the only cancer with evident cause and can be eliminated through early intervention. Developed by New Horizon Health, CerviClear is the first Urine-based HPV Detection and Cervical Cancer Screening Test in the world . It is the only product comprehensively covering all 14 high-risk HPV virus and achieves non-invasive home-based urine self-sampling. The product has already obtained a CE Mark, and is qualified for launching in Hong Kong and the Greater Bay Area.

Mr. Leslie Lu, Executive Director and Co-CEO of EC Healthcare said, "We are glad to partner with New Horizon Health, a leading cancer screening company. The Group treasures strategic cooperation with upstream partners in the pharmaceutical field as the core strategy. Through collaboration with partners in biotech and pharmaceutical industry, the Group will further improve the preventive medicine market influence and further consolidate its industry leading position. This Partnership enables the Group to further diversify its service product mix by leveraging vaccination, health check and multiple medical specialties services to complete the one-stop ecosystem. We believe the collaboration will also accelerate the Group to achieve vertical integration of the industry value chain."

Mr. Zhu Yeqing, Executive Director and CEO of New Horizon Health said: "The effective way to promote the prevention of high-risk cancer is to provide convenient, reliable and compliant innovative screening products. CerviClear is the first product in the world that achieves urine self-sampling. Compared with the clinical examination, patients no longer needs to visit a hospital and the sampling procedure is non-invasive and painless. It is expected to significantly lower the time cost and pressure level for patients. EC Healthcare is the leading healthcare services provider in both Hong Kong and the Greater Bay Area. We are glad to partner with EC Healthcare and believe the partnership becomes a milestone for our pipeline and innovation commercialization."

About EC Healthcare
EC Healthcare is Hong Kong's largest non-hospital medical service provider*, leveraging its core businesses of preventive and precision medicine, and committed to developing medical artificial intelligence by integrating its multi-disciplinary medical services. The move, which is supported by the Group's high-end branding and quality customer services, is aimed at offering customers safe and effective healthcare and medical services with professionalism. The Group is a constituent stock of the Hang Seng Composite Index and the MSCI Hong Kong Small Cap Index.

The Group principally engages in the provision of one-stop medical and health care services in Greater China. The Group provides a full range of services and products under its well-known brands, including those of its one-stop aesthetic medical solutions provider DR REBORN which has ranked first in Hong Kong by sales for years, a professional hair care center HAIR FOREST, primary care clinics jointly established with health management centre re:HEALTH, a vaccine centre Hong Kong Professional Vaccine HKPV, General outpatient clinic Tencent Doctorwork, the largest one-stop pain management centre in Hong Kong New York Medical Group, the comprehensive dental centres Bayley & Jackson Dental Surgeons, EC DENTAL CARE and Health and Care Dental Clinic, an advanced diagnostic and imaging centre HKAI, an oncology treatment centre reVIVE, a day procedure centre HKMED, a specialty clinic PREMIER MEDICAL CENTRE, SPECIALISTS CENTRAL and NEW MEDICAL CENTER, a paediatric centre PRIME CARE, a gynaecology specialist ZENITH MEDICAL CENTER AND PRENATAL DIAGNOSIS CENTRE, PathLab Medical Laboratories, Ophthalmology Center VIVID EYE and EC Veterinary Hospital and Imaging Center.

*According to independent research conducted by Frost and Sullivan in terms of revenue in 2020 and 2021

About New Horizon Health
Founded in 2015, New Horizon Health is a pioneer and leader in China's cancer screening market, focusing on early home screening of high-incidence cancers, aiming to promote innovation in cancer screening technology and accelerate the popularity of cancer screening technology in China. On February 18, 2021, New Horizon Health was successfully listed on the SEHK with stock code 6606.HK, which became "the first listed Chinese cancer early screening company".

New Horizon Health has three marketed products. ColoClear, Pupu Tube and UU Tube have all been approved by the National Medical Products Administration of China and are officially commercialized. ColoClear is the only cancer screening product approved by the National Medical Products Administration of China for people aged 40-74 who are at high risk of colorectal cancer. UU Tube is the only consumer self-test product for Helicobacter pylori approved by the National Medical Products Administration of China. Pupu Tube is the first FIT at-home self-test device approved in China. In addition, the Company has three pipelines of products in development for liver cancer (LiverClear), cervical cancer (CerviClear ) and nasopharyngeal cancer screening. The Company has global rights to all of its marketed and pipeline products.

New Horizon Health works extensively with hundreds of hospitals, health check-ups, insurance companies, pharmacies and online channels. The Company has a class 100,000 clean production workshop that meets ISO13485 and ISO9001 international certification standards. The third parties medical testing laboratories in Beijing, Hangzhou and Guangzhou have been certified by international quality standards and the local health care commission and issued licenses to practice, with an annual testing capacity of 2 million people.


Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com
GigaCloud Technology Inc Ushering In A Bright Future As China Reopening in 2023

HONG KONG, Mar 24, 2023 – (ACN Newswire) – In the past three years, with the weakness of overseas consumption and the impact of the new crown epidemic, the pattern of overseas shopping is changing considerably. People's shopping habits gradually shift from the original cross-border e-commerce to interest e-commerce and AI e-commerce. China, the world's largest goods trader, will reopen in 2023. Thousands of buyers and sellers are flocking to the new cross-border e-commerce led by TikTok, Pinduoduo, and GigaCloud. GigaCloud Technology Inc, which went public at the end of last year, once again impresses investors with its remarkable financial performance and demonstrates its superior strength and unlimited potential.


Source: Prospectus


First, Remarkable 2022 financial performance with impressive 3P Seller

On March 17, GigaCloud Technology Inc (Nasdaq: GCT) ("GigaCloud" or the "Company") released its financial results for the fourth quarter of 2022 ("Q4-22") and the full year of 2022 ("FY22"). Total revenues were US$490 million for FY22. Net income was US$23.97 million for FY22, including US$12.48 million in Q4-22, an increase of 34% compared to last year; operating profit for the year reached US$41.84 million, including US$15.19 million in Q4-22, an increase of 35% compared to last year; meanwhile, net cash flow from operating for FY22 increased by 480% to US$49.66 million, with the growth rate far exceeding market expectations.

Regarding specific products, 3P seller GMV grew 64% year-on-year to US$258 million in FY2022. GigaCloud Marketplace GMV grew 25% year-on-year to US$518 million, with a steady growth trend in trading users, with active buyers growing 17% year-on-year to 4,156 in FY22 and active sellers growing 47% year-on-year to 560 in FY22.

GigaCloud has formed a specific brand effect in the large merchandise foreign trade industry through its technology and scale effect. In particular, the performance of 3P seller was impressive. 3P seller GigaCloud Marketplace GMV was US$257.7 million in FY22, growing significantly compared to last year. 3P seller GigaCloud Marketplace GMV represented 50% of total GigaCloud Marketplace GMV in Q4-22 for the first time, showing a rapid growth trend.

Second, GigaCloud can release great potential as China reopens in 2023 to create a prosperous cross-border trade environment

1. Global leading B2B e-commerce solution provider – GigaCloud Technology Inc (GCT.US)

GigaCloud is currently the world's most advanced B2B e-commerce solution provider, mainly providing optimal cross-border solutions that allow products to be delivered from manufacturers and online distributors to terminal customers without borders. Through its unique artificial intelligence technology, GigaCloud digitizes sellers' credit profiles and then combines that data with the capacity of local warehouses, significantly increasing the utilization of warehouses. From the perspective of sales per unit area, GigaCloud enables the delivery of more goods than competitors.

In August 2022, GigaCloud went public on NASDAQ and was one of the few cross-border e-commerce platforms with AI technology. As of March 2022, GigaCloud Marketplace, GigaCloud's unique self-built stations, had 410 active 3p sellers and 3,782 active buyers. In the 12 months ended March 31, 2022, GigaCloud Marketplace GMV was US$438 million and spend per active buyer was US$116,000, showing that users are more willing to pay.

2. Well-developed logistics systems and outstanding self-built stations

In the course of e-commerce development, logistics is the foundation and support of e-commerce development, and the importance of logistics is self-evident. And relying on traditional cross-border logistics to transport goods has been difficult to meet the current needs of the rapid development of cross-border e-commerce. The traditional cross-border logistics sends parcels to consumers, which has the disadvantages of slow delivery, slow customs clearance, easy-to-lose packages, difficult to return, etc., and is also very easy to be restricted by the immigration policies of various countries.

In this context, the birth of overseas warehouses greatly solves the emergence of such problems. Overseas warehouses are established locally and used to store goods, so warehouses can directly dispatch goods after buyers place orders, which not only reduces the logistics costs of cross-border e-commerce merchants, but also avoids the drawback of long waiting time for buyers. Therefore, having a perfect warehouse and logistics network is the most favorable strength for cross-border e-merchants.

GigaCloud has operated 21 large-scale warehouses in North America, Europe, and four Asian countries. The warehouses have significantly optimized buyers' shopping experience while also greatly reducing merchants' high logistics costs and delivery time. GigaCloud currently has a total storage space of over 4 million square feets, covering 11 destination ports, with more than 10,000 containers per year, and has strong logistics and transportation advantages.

Meanwhile, GigaCloud also has the best AI system currently available, which can generate seller ratings and credit profiles through transaction volume and reasonably allocate warehouse delivery times based on credit ratings, thus significantly improving warehouse utilization. At the same time, GigaCloud also has an extensive shipping and trucking network, providing customers with fixed rates below market standards (FedEx, UPS) despite high shipping rates running at high costs.

GigaCloud's largest market is now mainly in the U.S. The Company also has in-depth cooperation with Rakuten in Japan, Walmart and Amazon in the U.S., and Wayfair in the U.K.. Moreover, the GigaCloud Marketplace, the Company's self-built station, has done quite well. In 2020, GigaCloud Marketplace had 210 active third-party sellers and 1,689 active buyers. Furthermore, GigaCloud Marketplace GMV reached over US$190 million. The number is still growing. As of March 2022, there were over 3,700 active buyers on the GigaCloud Marketplace, with GigaCloud Marketplace GMV exceeding US$440 million. The average annual expenditure per buyer on GigaCloud was US$116,000, showing outstanding microtargeting.

3. GigaCloud's current share price is cost-efficient and its P/B is low

GigaCloud currently has 3 main businesses, Gigacloud 1P, Off-platform ecommerce and GigaCloud 3P, which account for 45.45%, 30.81% and 23.74% of the Company's revenues, respectively. According to the prospectus, GigaCloud's total revenues in the past three years (2019, 2020, 2021) were US$122 million, US$276 million, and US$414 million, representing 125.3% and 50.4% year-over-year growth in 2020 and 2021, respectively; gross profits were US$22.2 million, US$75.1 million, and US$89.6 million, with 238% and 19.3% year-on-year growth in 2020 and 2021, respectively, representing 18.1%, 27.3% and 21.6% of total revenues, respectively. Under the global pandemic of Covid-19 and lingering weakness in overseas consumption, having such a growth trend is already a good achievement for the Company.

As of the closing quotation on March 17, 2023, GigaCloud's share price was US$5.27 per share, the after-hours price was US$5.26 per share, and the P/B was 1.098X. Amazon (AMZN.US)'s P/B is 6.94X, and Ebay's P/B is 4.38X. Regarding the P/B, GigaCloud's current share price is cost-efficient. From the perspective of the P/E, GigaCloud's P/ETTM is 9.31X, and P/ELYR is 9.31X, which are at the average of the industry level.

4. Global consumption is weak, while China market has more development opportunities

Most sellers are adopting a conservative stocking strategy in 2022 due to weak overseas consumption and shipping costs still running at a high level. According to the data from YUGUO's research, 64% of sellers are reducing the amount of stocking, 22% are preparing normally, and only 14% said they would increase the amount of stocking for the peak season.

In addition, cross-border logistics enterprises have also suffered setbacks. High inflation in Europe and the U.S., changing overseas tariff policies, and frequent overseas inspection and supervision have harmed some goods, logistics routes, and even prices. According to the data from Shanghai Shipping Exchange, Shanghai Containerized Freight Index (SCFI) exceeded 5,000 points in January 2022, while the index dropped to 1,031.42 points as of January 13, 2023, with a significant decline in shipping prices.

With the rise in logistics and various labor costs, several cross-border platforms also raised the fees for related services last year: Tiktok shop launched a cross-border store margin policy, Amazon raised FBA fees for multiple stations, and Pinduoduo's TEMU also reduced the proportion of shipping costs borne by the platform itself. Due to the dual pressure of platform and logistics, the number of containers in the U.S. in December 2022 was 19.3% lower than in December 2021, according to data published by Descartes, with a significant surplus of shipping space. Although the liner transport companies took the initiative to reduce the actual capacity allocation, transport prices continued to fall as supply outpaced demand.

China is the world's largest country in goods trade. As China reopens in 2023, China is expected to bring extraordinary vitality to the global market. According to data from Intelligence Research Group, from 2017 to 2022, the market size of China's export cross-border e-commerce has remained stable at more than 75%, and the market size of China's imported cross-border e-commerce is RMB 3.2 trillion in 2021, accounting for 22.54% of the total cross-border e-commerce market size.

As the market penetration of global e-commerce continues to rise, the Chinese market will release more significant potential. With the high-quality transformation and upgrading of the domestic manufacturing industry, the production quality and efficiency of domestic processing and manufacturing are significantly improved. As "Made in China" moves to the international stage, it will also drive the rapid growth of China's cross-border e-commerce demand.

Third, with the rapid recovery of cross-border e-commerce, GigaCloud will usher in a bright future

Cross-border e-commerce is the most direct way of economic trade between countries, and its strategic position is unshakable. Although the global economy is slightly weak at present, the domestic market scale of cross-border e-commerce has maintained steady growth year-round. In addition, in January 2023, China's Ministry of Finance and three other departments jointly issued the "Announcement on Tax Policy of Goods Returned from Cross-border E-commerce Export" to introduce VAT, consumption tax and tariff exemptions to encourage the development of cross-border e-commerce, which will increase the business volume of cross-border e-commerce and drive domestic export business. In addition, as China reopens in 2023 after epidemic, the cross-border trade is expected to return to the pre-epidemic state.

GigaCloud has formed a specific brand effect in the large merchandise foreign trade industry. The self-built stations and AI algorithms for warehousing and logistics have brought cost advantages to sellers and established a unique strength in the ecology. The total revenue of GigaCloud Marketplace, the Company's self-built station, has grown at a high rate of more than 50% in the past three years against a background of global epidemic and sluggish market environment, demonstrating the Company's competitiveness. From the 2022 financial report, 3P Seller has also gradually become a profit growth point for the Company. 3P seller GigaCloud Marketplace GMV represented 50% of total GigaCloud Marketplace GMV in Q4-22 for the first time, showing a rapid growth trend. However, a certain interest rate spread exists between the Company's current share price and its real value. Compared with Amazon and eBay, GigaCloud's current P/B (1.098X) appears to be more valuable. With the extensive self-built warehouse layout and cutting-edge digital technology, GigaCloud will stand out from its competitors by leveraging its unique advantages and will bring long-term and stable investment returns to investors.


Copyright 2023 ACN Newswire. All rights reserved. http://www.acnnewswire.com